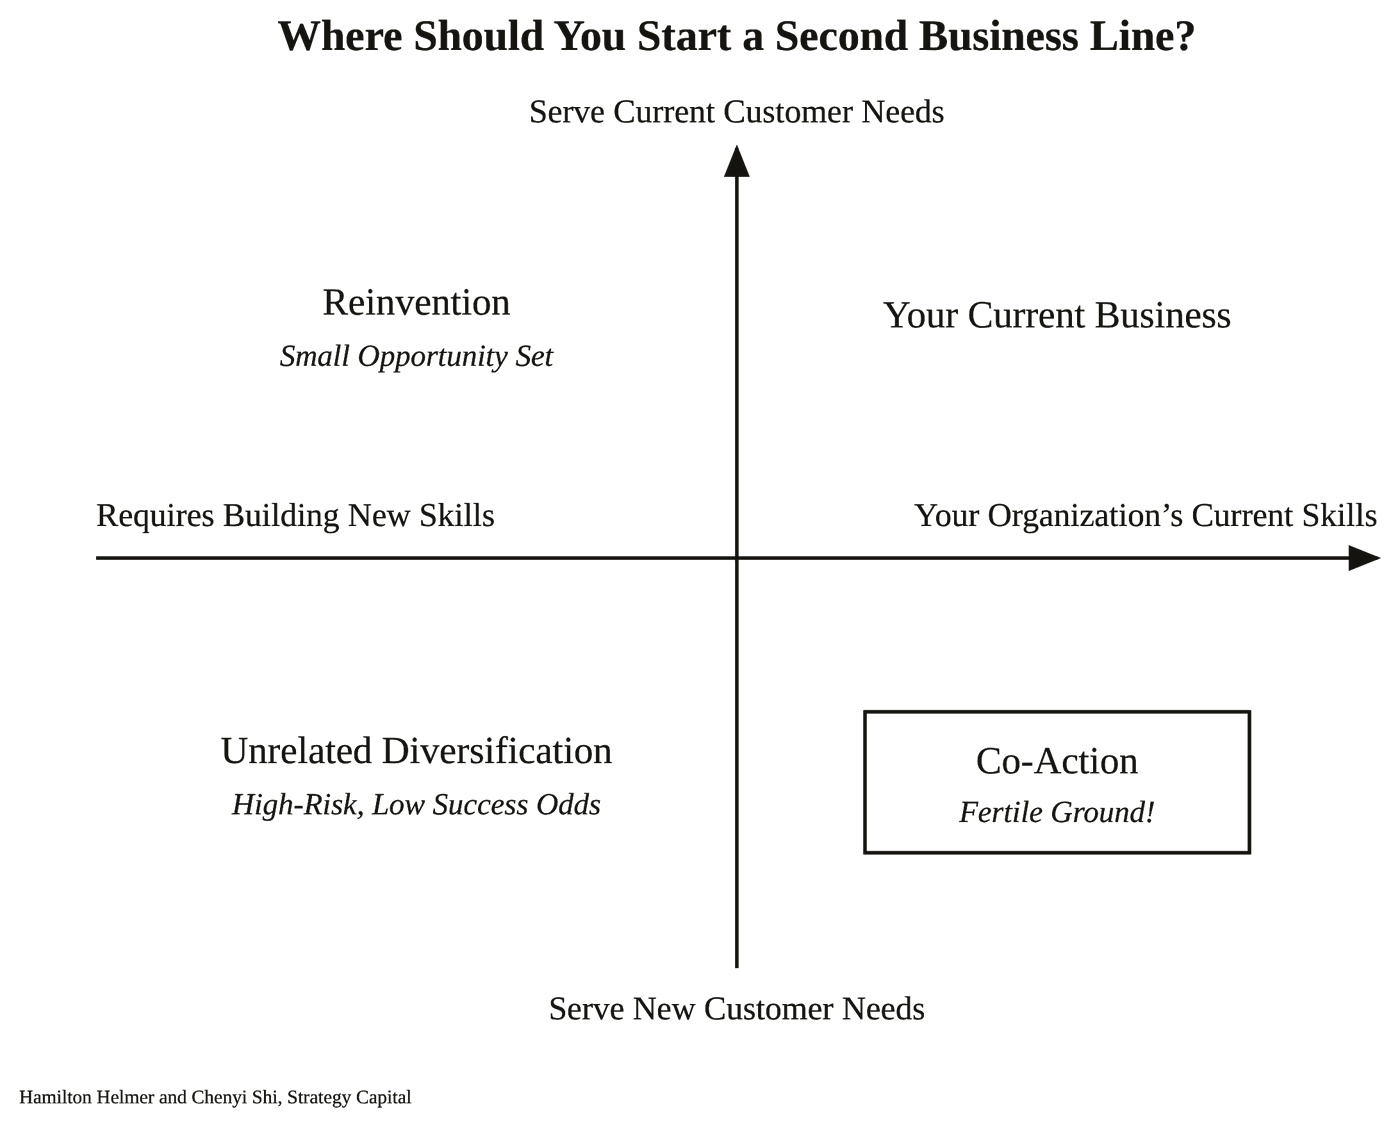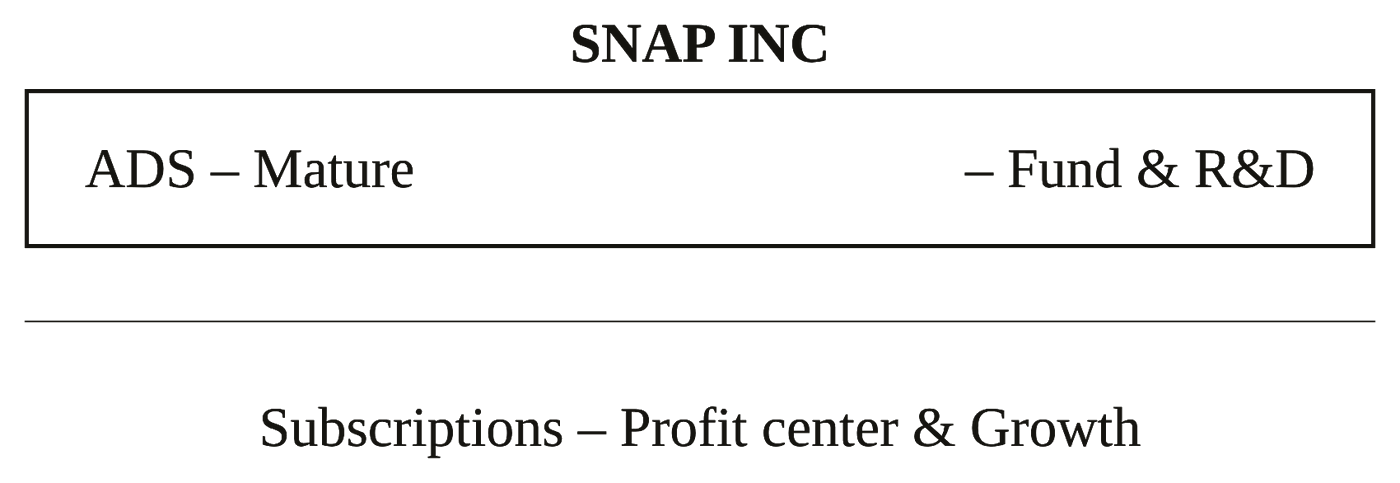
Snap Inc.’s business model is changing. Wall Street has tagged the company as an advertising company, which has been the dominant model for most of the company’s short time in the public market (9 years). But over the last two years, it has seen growth in one segment that is unrelated to advertising and has a marginal cost of selling near zero. Snap+ is the subscription business for Snapchat’s app. I believe that this is the future; most tech companies’ dominant revenue today comes from a second business like AWS or Windows.
The limits of Snapchat’s advertising business
Snap Inc currently has advertising as its dominant revenue source. And it has a unique offering through its AR filters, as a way to display ads, along with real estate in the apps, Maps, and contacts, and through its feed of videos. Snap had 5.9 billion in revenue in FY2025. Ads were 87% of revenue. I view this business as the legacy business, and I expect revenue to still come from it at a high rate, but the higher-margin revenue and the growth driver will come from Snap +.
The reason why the ad business has struggled compared to Meta is structural. Meta has products that, with every interaction, give them more data about a user, whereas Snap’s core value proposition is how everything is temporary, and they are a messaging platform, so there is inherently much less data anyway. Apple’s ATT privacy rules have further impacted Snap’s ability to track data, which helps it sell targeted ads, which is much harder for Snap than for its competition. Snapchat + is a subscription service where users get experimental, pre-release, and exclusive features.
Snapchat+ pricing and subscription economics
Annual Plan - $2.25/mo Monthly Plan - $4.49/mo Lens+ - $7.99/mo
Platinum - $13.49/mo Family Plan - $6.49/mo Snap has provided guidance that “direct revenue” will have a 1 billion annualized revenue run rate in 2026. The key thing is that the marginal cost to serve the next user for this is near zero. The only real cost is the cut they pay through Apple.
| Metric | Q1 2024 | Q2 2024 | Q3 2024 | Q4 2024 |
|---|---|---|---|---|
| Other Revenue ($M) | 87 | 107 | 123 | 143 |
| Subscribers (M) | 9.4 | 10.3 | 12.0 | 14.0 |
| Blended ARPU / Month ($) | $3.09 | $3.46 | $3.42 | $3.40 |
| YoY Revenue Growth | 194% | 194% | 194% | 194% |
| ARR Run Rate ($M) | 348 | 428 | 492 | 572 |
FY Total Other Revenue ($M): 460
| Metric | Q1 2025 | Q2 2025 | Q3 2025 | Q4 2025 |
|---|---|---|---|---|
| Other Revenue ($M) | 152 | 175 | 190 | 232 |
| Subscribers (M) | 15.0 | 16.0 | 20.0 | 24.0 |
| Blended ARPU / Month ($) | $3.38 | $3.65 | $3.17 | $3.22 |
| YoY Revenue Growth | 194% | 194% | 194% | 194% |
| ARR Run Rate ($M) | 608 | 700 | 760 | 928 |
FY Total Other Revenue ($M): 749
| Metric | Q1 2026 | Q2 2026 | Q3 2026 | Q4 2026 |
|---|---|---|---|---|
| Assumed YoY Growth Rate | 60% | 55.0% | 46.0% | 50.0% |
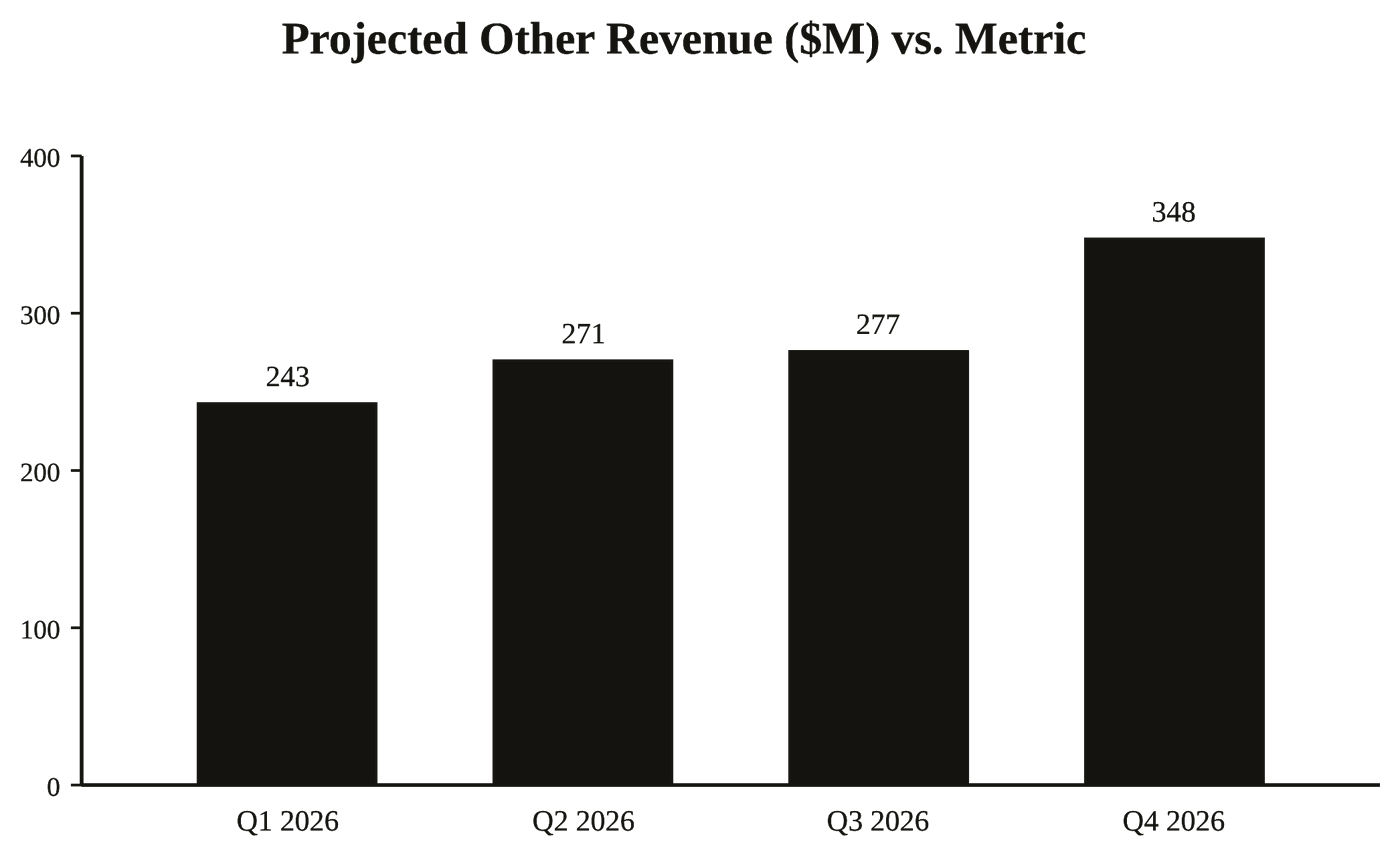
| Projected Other Revenue ($M) | 243 | 271 | 277 | 348 |
| Projected Subscribers (M) | 26.0 | 28.0 | 30.0 | 32.0 |
| Projected Blended ARPU / Month ($) | $3.12 | $3.23 | $3.08 | $3.63 |
FY 2026 Projected Revenue ($M): 1,140
Network effects support the subscription business
Snap has the network effects currently for this transition to work. Advertising is sound, it’s just harder for the platform as stucturally the lack of targetted data. The combination of both can make Snap a great business, and the stock should recover well.